Personal Finance Tips for 2026: A Practical Money Playbook
Most personal finance advice fails for a simple reason: it assumes you have unlimited willpower and a spreadsheet habit. Real life is messier. Bills arrive at awkward times, prices keep shifting, and good intentions fade by the second week of the month. The personal finance tips in this playbook are built for that messy reality, focusing on small systems that keep working even when your motivation does not.
I have coached friends and readers through debt payoffs, first emergency funds, and their first invested dollar, and the pattern is always the same. The people who win do not try harder; they set up smarter defaults. Below are the habits, numbers, and tools that consistently move the needle in 2026. If you want a running list of vetted apps to support these habits, keep the reviews at personal finance tips handy as you read.
Start With the Only Number That Matters
Before budgets, before apps, before investing, find your cash-flow number: money in minus money out each month. If it is positive, you have a surplus to deploy. If it is negative, no investment strategy will save you until you fix the leak. This single figure tells you the truth faster than any app dashboard.
Track it for one month without judgment. Just watch. The Consumer Financial Protection Bureau recommends this kind of plain observation before making changes, because you cannot manage what you have never measured. Most people are shocked by how much slips out through small, forgettable purchases.
How much should you keep in an emergency fund?
A practical target is three to six months of essential expenses, but do not let that intimidate you. Start with a $1,000 mini-fund, then build from there. The goal is to stop a flat tire or a surprise bill from becoming a credit-card spiral. Keep this money in a separate high-yield account so it is close enough to reach but far enough not to spend by accident.
Personal Finance Tips That Beat Willpower
Willpower is a battery that drains by evening. The strongest personal finance tips replace it with automation and structure. Here are the ones I lean on most.
- Pay yourself first. Automate a transfer to savings the day your paycheck lands.
- Use the 50/30/20 frame. Roughly half for needs, a third for wants, a fifth for saving and debt.
- Freeze impulse buys. Give any purchase over $100 a 24-hour waiting period.
- Kill zombie subscriptions. Audit recurring charges every quarter.
- Round up spare change. Let micro-savings tools capture what you would not miss.
None of these require heroic discipline. They work because they run in the background, turning good behavior into the path of least resistance.
A simple monthly money routine
- On payday, automate savings and bill payments first.
- Mid-month, check your cash-flow number against your plan.
- End of month, audit one category where you overspent.
- Quarterly, review subscriptions and nudge your savings rate up.
Managing Everyday Money With the Right Tools
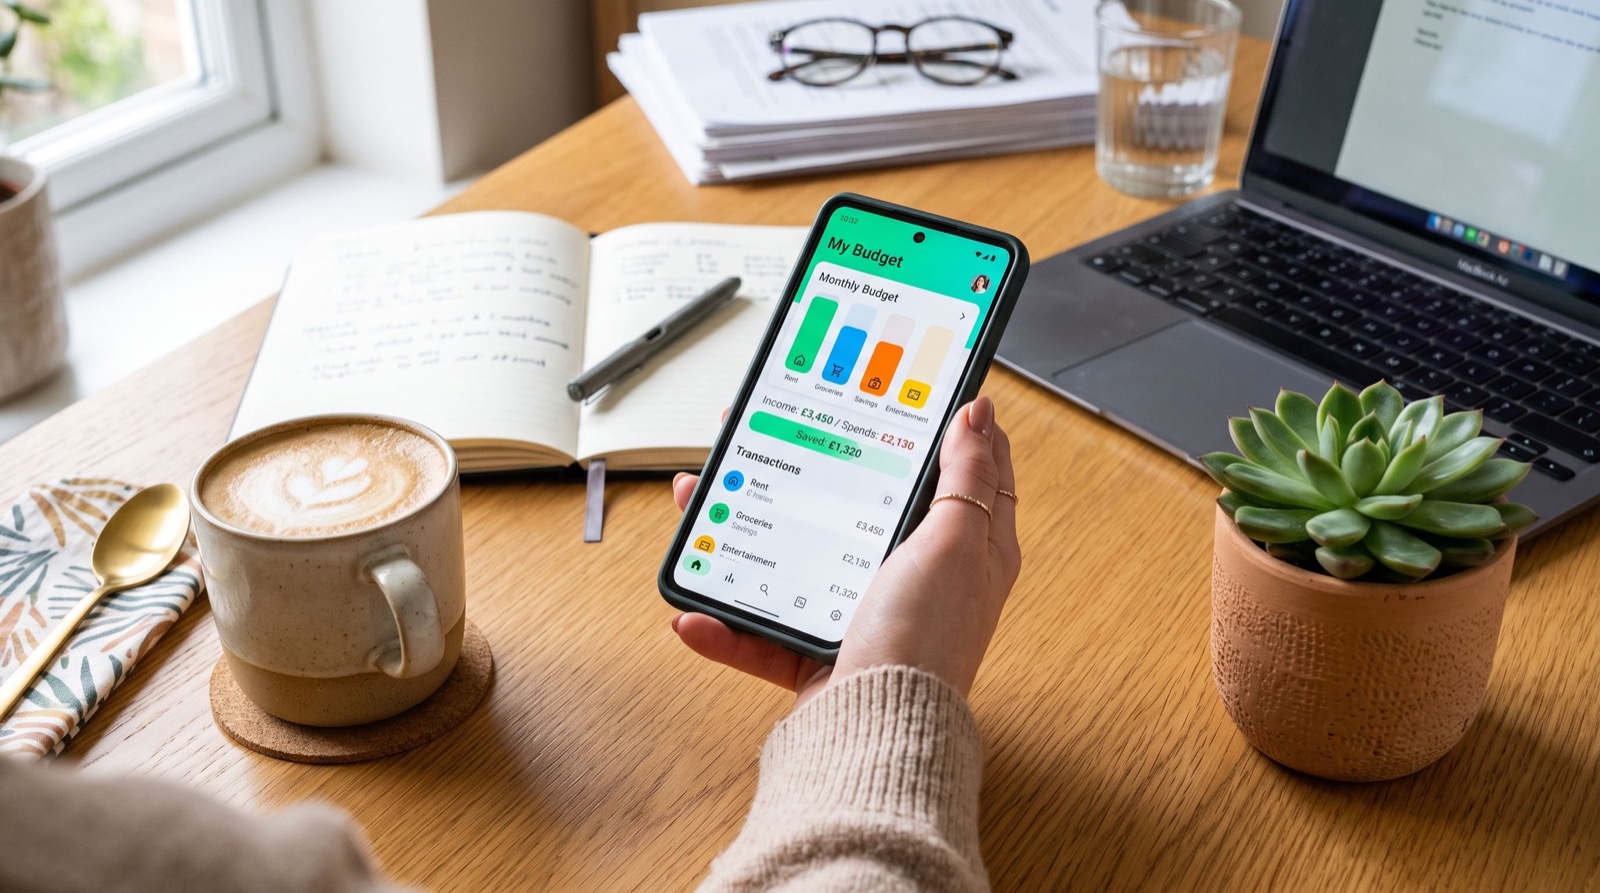
Digital wallets have become the default way to move money between friends, family, and small businesses. Used well, they make splitting rent or reimbursing a coworker instant and painless. Used carelessly, they leak money through instant-transfer fees and untracked balances.
Cash App is a common entry point because it blends payments, a debit card, and basic investing. If you rely on it, read a careful Cash App guide so you understand which transfers are free, how the Cash Card fits your budget, and how to lock down your account against fraud.
| Money goal | First action | Timeframe |
|---|---|---|
| Stop overspending | Track cash flow for 30 days | 1 month |
| Build a buffer | Save a $1,000 mini-fund | 3–6 months |
| Escape high-interest debt | Attack the highest APR first | 6–18 months |
| Start investing | Automate into a low-cost index fund | Ongoing |
Debt and Interest: Play Offense
High-interest debt is the fire you put out before doing anything else. Credit-card APRs in 2026 remain steep, and Investopedia notes that carrying a balance can quietly erase any return you might earn elsewhere. Prioritize the highest-rate balance first while paying minimums on the rest, a method that saves the most money mathematically.
If motivation matters more to you than math, pay off the smallest balance first for a quick psychological win, then roll that payment into the next debt. Either method works. The wrong move is paying only minimums forever and letting interest compound against you.
One original tip most guides skip
Automate a tiny “annoyance fund” of $25 a month for the small irritations that usually trigger overspending, like a broken charger or a forgotten birthday gift. Having a dedicated pool for life’s papercuts stops them from blowing up your main budget, and it removes the guilt that often spirals into more spending.
Grow the Surplus, Don’t Just Hoard It
Once your buffer is solid and high-interest debt is gone, put your surplus to work. Automate contributions into a low-cost, diversified index fund and leave them alone. Time in the market, not timing the market, is what compounds. Even modest monthly contributions grow meaningfully over a decade.
For entrepreneurs, the same discipline applies to business finances. Aligning your personal money systems with professional guidance from dependable specialists can help you separate personal and business cash flow cleanly, which protects both.
Frequently Asked Questions
What are the most important personal finance tips for beginners?
Start by tracking your cash flow, build a small emergency fund, automate savings on payday, and attack high-interest debt first. These four personal finance tips create a stable base before you worry about investing or optimizing.
How do I stick to a budget when my income varies?
Budget from your lowest recent month, automate savings on every payday regardless of size, and keep a buffer to smooth lean weeks. Variable income needs a larger emergency fund and flexible want-category spending.
Are money apps safe for managing personal finances?
Reputable apps use bank-level encryption, FDIC-insured partners, and two-factor login. They are safe when you enable every security feature, use unique passwords, and never share verification codes with anyone who contacts you first.
How much should I save each month?
Aim for at least 20 percent of income toward saving and debt, but start with whatever is sustainable. Consistency matters more than size; automate a small amount and raise it one percentage point each quarter.
Conclusion
Solid personal finance in 2026 is less about willpower and more about smart defaults: know your cash-flow number, automate saving, crush high-interest debt, and let a diversified index fund grow your surplus. Pick one tip from this playbook and set it up today. Then explore vetted money tools to support the habit, and let your systems keep working long after the motivation fades.